Money tools are powerful and dangerous in equal measure. This department teaches budgeting, mobile money, saving and borrowing with clear eyes — and how to recognise the scams that target everyone with a phone.
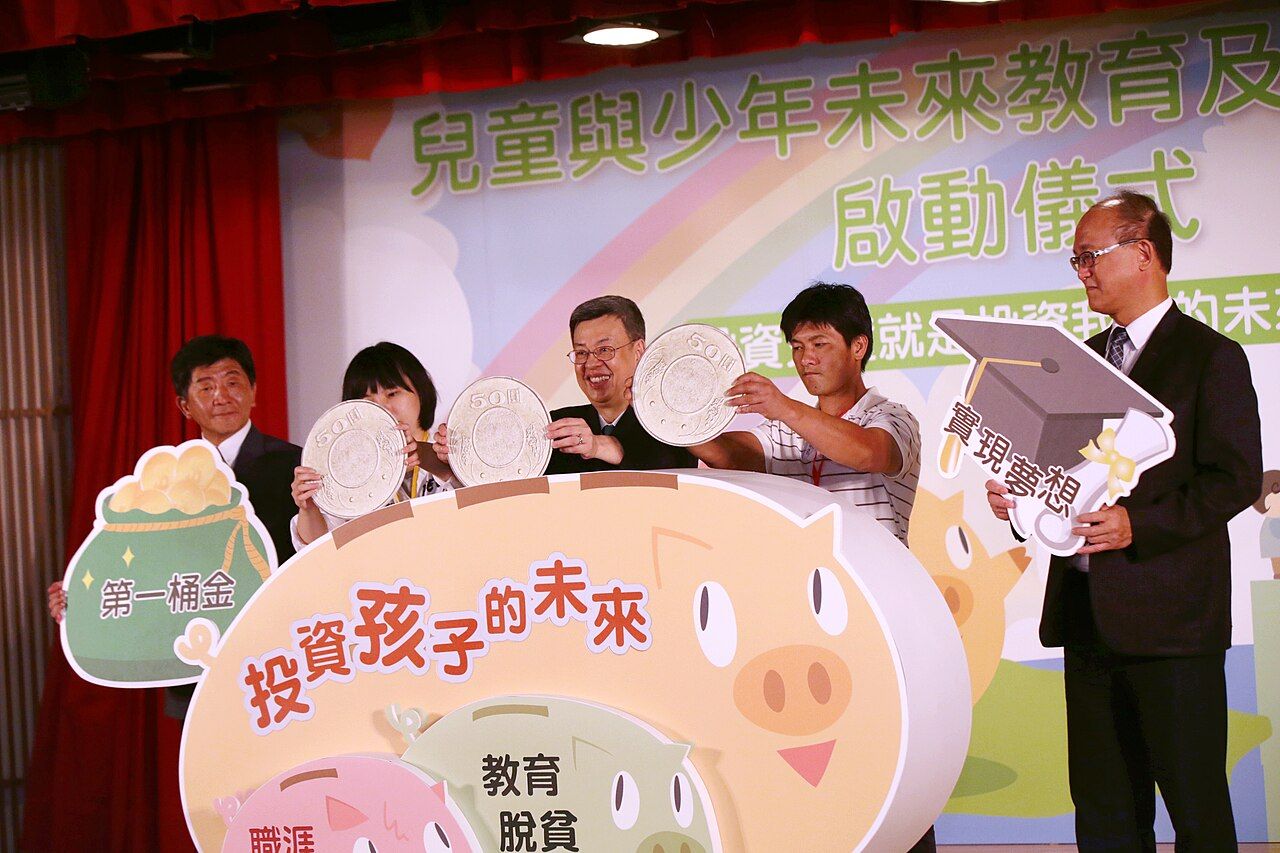
A children's savings-account launch ceremony in Taiwan. Photo: 總統府 · CC BY 2.0 · source
A savings jar — small amounts, kept faithfully, grow. Photo: stevepb · CC0 · source
Five guided solutions
Each solution follows the Global Solutions pattern: the problem, how it works, the steps, the outcome you can expect — and the boundary where a licensed professional must take over.
Solution 1 of 5
A household budget that holds
The problem. Most budgets fail by February because they are wishes, not systems: built on hoped income, silent about irregular costs, and abandoned at the first emergency.
How it works. A holding budget starts from real numbers — what actually arrived and left over the last three months — separates needs from wants honestly, and gives savings a payday appointment like any other bill.
Practical steps
Track every expense for one month without judging it; just record.
Sort the record into needs, wants, and surprises that recur (school fees, repairs, festivals).
Build the monthly plan from average real income, not the best month.
Assign savings a fixed transfer on payday, however small.
Review for fifteen minutes monthly and adjust one thing at a time.
Expected outcome. A plan that survives real life — and savings that grow quietly in the background.
⚠ Professional boundary. A budget is a household tool, not financial advice for investments; for significant debts or investments, consult a licensed adviser.
Solution 2 of 5
Use mobile money safely
The problem. Mobile money has banked millions — and attracted fraudsters in equal measure. Most losses come not from hacked systems but from persuaded people.
How it works. The rules are few and absolute: your PIN is yours alone; no genuine agent or company will ever ask for it; every 'reversal', 'prize' or 'wrong transfer' call is a script until proven otherwise — and proof comes only from the official channel, dialled by you.
Practical steps
Memorise your PIN; never write it on the phone or share it with agents.
Verify every transaction on your own phone's official menu before acting on any message.
Treat unexpected calls about your account as fraud until you have called the official number yourself.
Check the recipient's name on screen before confirming any send.
Keep transaction records; report problems to the provider immediately.
Expected outcome. The convenience of mobile money without its traps.
⚠ Professional boundary. If money has left your account through fraud, contact the provider and police at once — speed matters more than embarrassment.
Solution 3 of 5
Spot the scam before it spots you
The problem. Investment scams promise what honest markets never can: high returns, guaranteed, with no risk — and they arrive dressed as friends, pastors, officials and celebrities.
How it works. Every legitimate investment can explain how returns are generated, is registered with the regulator, and lets you withdraw by clear rules. A scheme that fails any of these tests is not an opportunity; it is a collection plate for the operator.
Practical steps
Ask: how exactly does this make money? Vague answers end the conversation.
Check registration with your country's securities or financial regulator.
Refuse urgency — 'today only' is a pressure tool, not a fact.
Test withdrawal with a tiny amount before any serious sum — then still be careful.
Warn family members; scammers target whole networks through one believer.
Expected outcome. Savings protected by questions that take two minutes to ask.
⚠ Professional boundary. Report suspected schemes to the regulator and police; your report may save your neighbour's school fees.
Solution 4 of 5
Save with a goal and a system
The problem. 'I will save what is left' fails because nothing is ever left. Savings succeed when they are automatic, separated, and attached to a named goal with a date.
How it works. Give each goal its own place — a separate wallet, account or savings group — and a monthly amount derived from the goal and the date, not from mood. Watching a named fund grow ('Roof — 2027') sustains discipline that a vague balance cannot.
Practical steps
Name the goal and its deadline: what, how much, by when.
Divide the amount by the months remaining — that is the monthly duty.
Automate the transfer for payday, before spending begins.
Keep the fund where spending it requires deliberate effort.
Review progress quarterly; adjust the amount or the date honestly, never silently.
Expected outcome. Goals that arrive — a roof, a school year, a machine — funded month by ordinary month.
⚠ Professional boundary. Keep emergency savings separate from goal savings; raiding the roof fund for a crisis rebuilds neither.
Solution 5 of 5
Understand a loan before you sign
The problem. The advertised rate is not the cost of a loan. Fees, insurance, penalties and the repayment schedule decide what you truly pay — and a cheap-looking loan can be the dearest.
How it works. Ask for the total repayment amount in writing: every cedi, dollar or franc you will hand over from first payment to last. Compare loans on that number and on the monthly burden against your real budget — never on the headline rate.
Practical steps
Ask for the full cost: interest, fees, insurance, penalties — totalled in writing.
Confirm the payment dates and what happens if you pay late or early.
Test the monthly payment against your budget's worst month, not its best.
Borrow for what produces income or prevents greater loss — be honest about which.
Read every page before signing, and keep your own copy of the agreement.
Expected outcome. Credit used as a tool with a known price, instead of a trap discovered later.
⚠ Professional boundary. If repayments become impossible, contact the lender early — negotiated plans almost always beat silent default.